It sounds like six of one, half a dozen of the other. Your revocable trust says that after you and your spouse are both gone, your assets ultimately divide into separate trusts for your children. So when you are completing the beneficiary designation on your IRA, 401(k), or other retirement account, you or your financial advisor may reasonably ask:
Why can’t I just name my revocable living trust as the beneficiary and let the trustee divide everything later?
You can, but that doesn’t necessarily mean you should.
When I recommend naming your children’s separate sub-trusts directly as beneficiaries of retirement accounts, there is usually a reason: we are trying to keep a protected asset protected and avoid sending it through an unnecessary layer of administration.
Florida Gives Retirement Accounts Strong Creditor Protection
Florida has some of the strongest protections for retirement assets in the country. Florida Statute § 222.21 generally protects qualifying retirement accounts, including IRAs and many employer-sponsored retirement plans, from the claims of creditors. Importantly, Florida law also provides that qualifying retirement funds do not automatically lose that protection after the owner’s death simply because they are transferred to an inherited IRA. So when an asset already comes with a protective wrapper, I don’t want to unwrap it unnecessarily.
What Happens If Your IRA Is Payable to Your Revocable Trust?
Let’s use a common estate plan as an example. Husband names Wife as 100% primary beneficiary of his IRA. Wife names Husband as 100% primary beneficiary of hers. So far, so good.
For the contingent beneficiary, however, the financial advisor asks:
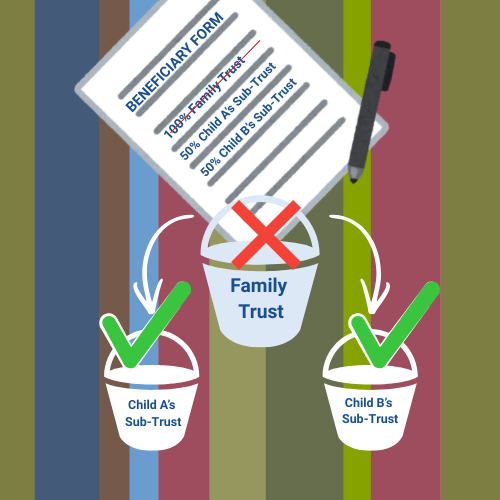
“Why don’t we just name the Family Trust? The trust eventually divides everything between the children anyway.”
That may produce the same ultimate beneficiaries, but it’s not the same path.
If the retirement account is payable first to the parents’ revocable trust, those assets enter the trust during the post-death administrative period. The trustee may be dealing with final expenses, taxes, administration costs, creditor issues, and all of the other work required before the remaining trust property is divided into the children’s separate trusts. Florida law specifically recognizes that a revocable trust may be called upon to pay certain expenses and obligations of the settlor’s estate when the probate estate is insufficient. See Florida Statutes §§ 733.707(3) and 736.05053. Florida law also contains important exceptions for assets that are otherwise protected from creditors, so this does not mean every IRA payable to a revocable trust suddenly becomes fair game for every creditor.
But from an estate-planning perspective, why make the retirement account take that trip if it doesn’t need to?
Direct to the Children’s Trusts Is Often the Cleaner Route
Suppose your estate plan creates:
- a separate trust for Child One; and
- a separate trust for Child Two.
Instead of naming the Family Trust as the contingent beneficiary of your retirement account, we may recommend designating those children’s trusts directly in the appropriate percentages. That can reduce administrative complexity and, depending on the circumstances, reduce the opportunity for creditor, jurisdictional, or asset-protection issues to arise along the way.
But Doesn’t Florida Protect My Revocable Trust Too?
Not in the same way. During your lifetime, assets in your ordinary revocable living trust generally remain reachable by your creditors because you still control those assets. Florida Statute § 736.0505 provides that property of a revocable trust is subject to the settlor’s creditors during the settlor’s lifetime to the extent the property would not otherwise be exempt if the settlor owned it directly.
A retirement account may have its own statutory exemption.
Cash or investments sitting in one’s own revocable trust generally do not acquire a magical creditor shield merely because the word “trust” appears on the account.
A revocable living trust is primarily an estate-planning and probate-avoidance tool. It is not, by itself, an asset-protection trust.
Your children’s continuing sub-trusts are a different story. Because they were not the grantor on those trusts, they’re “3rd party settled trusts,” and contain a level of asset protection your original trust doesn’t. They also may be drafted very differently, with spendthrift provisions and restrictions designed to protect inherited assets from certain claims against the children. Florida recognizes valid spendthrift provisions under Florida Statute § 736.0502, subject to statutory exceptions.
What If a Creditor or Beneficiary Is Outside Florida?
This is where planning gets even more important. Florida’s retirement-account protections are excellent. But families are mobile. Your children may not always live in Florida. A lawsuit may arise somewhere else. A trust may eventually be administered elsewhere. Choice-of-law and jurisdiction questions can become complicated very quickly. I do not like building an estate plan that depends on winning a future argument over which state’s creditor-protection law applies. When the retirement account can properly move directly into the intended beneficiary’s trust, that may give us a cleaner asset-protection path and avoid unnecessarily relying on intermediate protections.
That does not mean naming the revocable trust is always wrong. It means beneficiary designations should be coordinated with your attorney’s advice.
Retirement Accounts Also Have Their Own Tax Rules
There is another reason we pay so much attention to these beneficiary forms: retirement accounts do not behave like ordinary trust assets.
The SECURE Act substantially changed the distribution rules for inherited retirement accounts. For many non-spouse beneficiaries, the inherited retirement account generally must be fully distributed by the end of the tenth year following the owner’s death. Different rules can apply to surviving spouses, minor children of the account owner, disabled or chronically ill beneficiaries, and certain other beneficiaries.
A trust can qualify for favorable treatment as a retirement-account beneficiary, but the trust must satisfy specific federal requirements. Treasury regulations continue to recognize qualifying “see-through trusts,” under which certain trust beneficiaries are treated as the retirement-account beneficiaries if the required conditions are satisfied.
Please do not casually change the beneficiary of a large IRA because someone at the financial institution says, “Either way is fine.”
From the financial institution’s perspective, both beneficiary designations may be permitted. From an estate-planning, tax, trust-administration, and asset-protection perspective, they may not accomplish exactly the same thing.
Please contact our office if you have questions about the beneficiary or funding instructions we gave you with your estate plan.